Paying for a Hotel With a Debit Card Can Tie Up Hundreds of Dollars. Here’s How Holds Work
We may earn money or products from the companies mentioned in this post. This means if you click on the link and purchase the item, I will receive a small commission at no extra cost to you ... you're just helping re-supply our family's travel fund.
When you check into a hotel, the front desk usually places a hold on your card for the cost of the stay plus an extra deposit for incidentals. With a credit card, that hold just reduces your available credit. With a hotel debit card hold, the money comes straight out of your available checking balance, and it can stay locked up for several days after you check out.
That is how a three-night stay can tie up hundreds of dollars more than the room rate. If your checking account is tight, the hold can lead to declined purchases or overdraft fees, even though you have not actually been charged the extra amount.
The hold is not a scam or a mistake. It is how card payments work. But knowing how it works lets you avoid the surprise. Here is a clear explanation and what you can do about it.
How a hotel debit card hold works
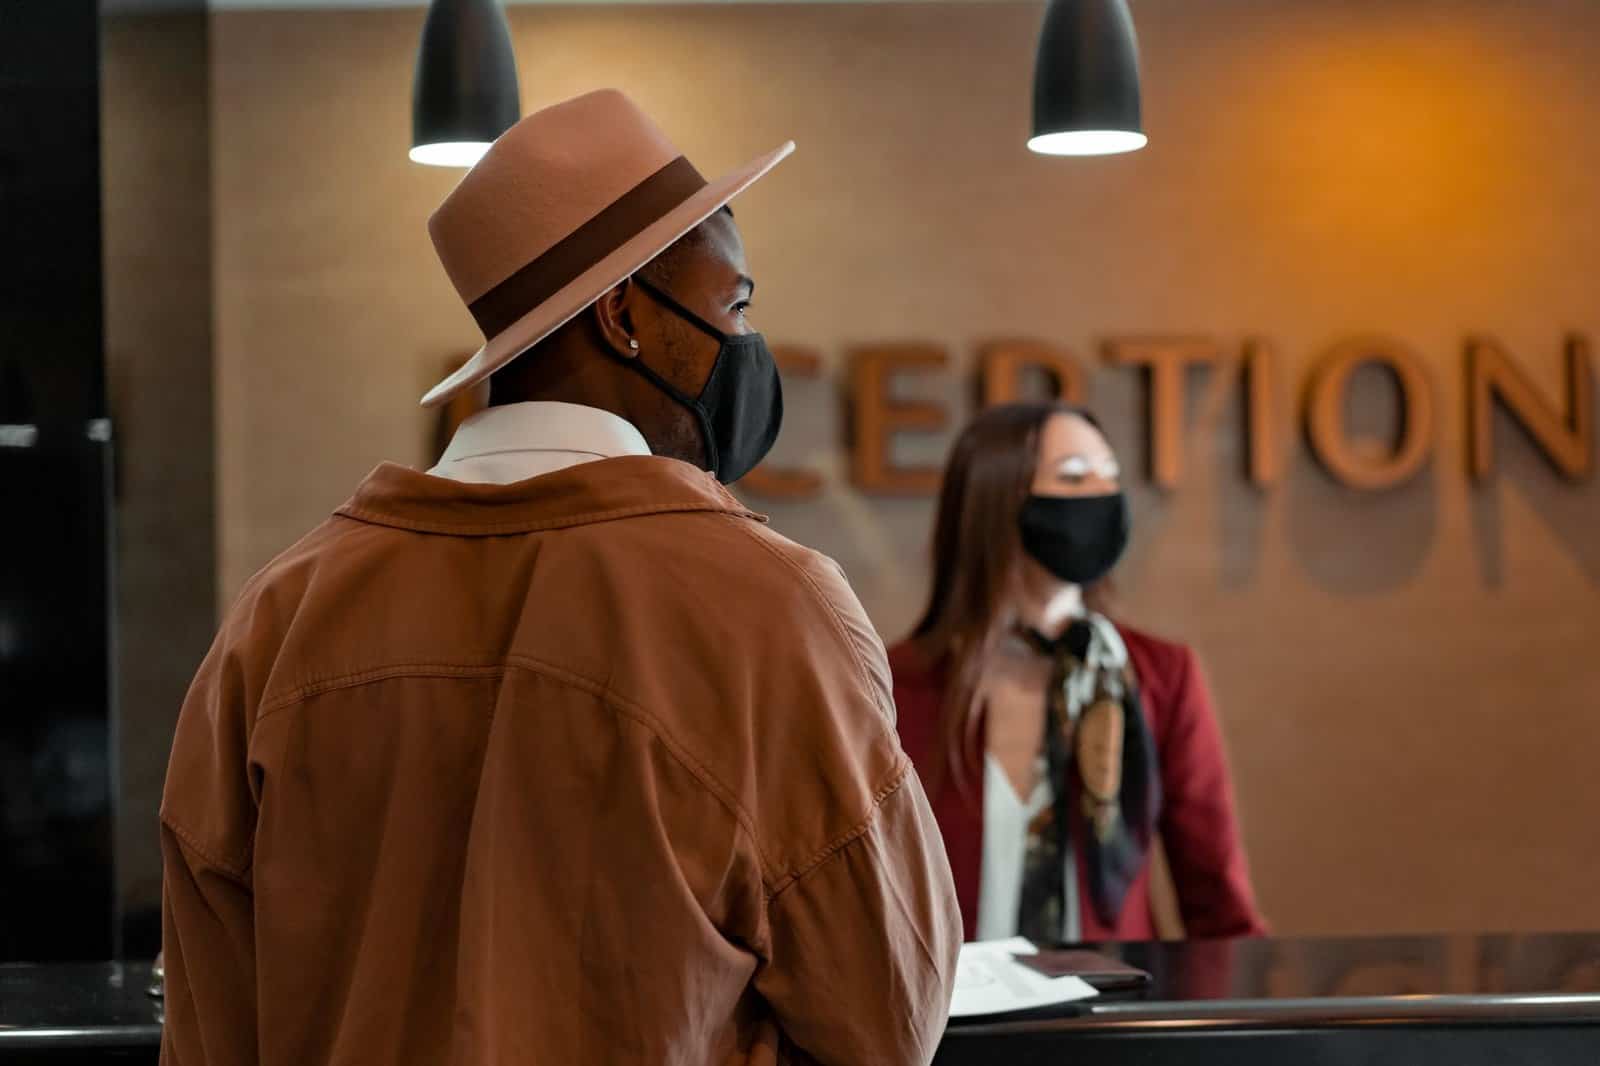
A hold, also called a pre-authorization, is a temporary block on funds. When you hand over your card at check-in, the hotel asks your bank to set aside a certain amount of money. The bank confirms the funds are available and blocks them so you cannot spend them elsewhere.
The hold typically covers two things:
- The room and taxes for your stay, unless you already prepaid.
- An incidental deposit to cover things like room service, minibar items, parking, damages, or late checkout fees.
Incidental deposits vary widely. Many hotels charge a flat amount per stay, while others charge per night. Amounts often run from around $50 to $200 per night, and upscale or resort properties can ask for more. Some hotels require a larger deposit when you pay with a debit card than with a credit card.
When you check out, the hotel charges your final bill. The hold should then be released. But “released” does not mean “immediately available.”
Why the money takes days to come back
The hotel’s final charge and the release of the original hold are separate actions. In many cases, your bank keeps the hold in place until the hotel’s final charge settles, which can take a few business days. If the final charge is less than the hold, the difference is released, but timing depends on your bank and the hotel’s payment processor.
Many banks release holds within a few business days, but it can take up to a week or longer in some cases. Weekends and holidays can stretch the delay. During that time, the money may still show as unavailable, even though the hotel has already charged you.
Why it matters more with debit than credit
With a credit card, a hold reduces your available credit. Unless you are close to your credit limit, you may not notice it. With a debit card, a hold reduces your available cash, the same money you use for groceries, gas, and bills.
That creates real risks:
- Declined transactions. If the hold eats up your available balance, other purchases can be declined during your trip.
- Overdraft fees. If you have overdraft coverage, purchases might go through but trigger fees.
- Bill payments failing. Automatic payments scheduled during your trip could bounce if your balance drops too low.
Credit cards also generally offer stronger consumer protections for disputes, which is another reason many travelers prefer them for hotels.
A simple example
Suppose you book a three-night stay at $150 per night, plus taxes, for a total of about $510. The hotel’s incidental deposit is $100 per night, or $300. At check-in, the hotel places a hold of about $810 on your debit card.
You check out after three nights with no extra charges. The hotel charges your final bill of $510. But until the original hold drops off and the charge settles, your bank may show $810 as unavailable, or even both the hold and the charge for a short time. If you started with $1,200 in your account, you may have less than $400 available during and shortly after your trip.
That is how a hotel stay can tie up hundreds of dollars more than you expected.
How to avoid problems with a hotel debit card hold
The simplest way to avoid hold issues is to use a credit card for hotel check-in. But if you do not have one or prefer debit, these steps help.
Ask about the hold before you book or check in
Call the hotel or check its policies online to find out:
- How much the incidental deposit is.
- Whether it is charged per night or per stay.
- Whether the hotel accepts debit cards for incidentals.
- Whether a larger deposit applies to debit cards.
Some hotels require a credit card for incidentals and may not accept debit at check-in, or may only accept it with additional conditions. Knowing this ahead of time avoids surprises at the front desk.
Keep a cash buffer
If you use debit, make sure your checking account has enough to cover the room, the hold, and your other trip expenses, plus a buffer for a few days after you check out. Plan as if the hold amount is unavailable for about a week.
Ask for the hold to be released at checkout
At checkout, ask the front desk to release the hold or confirm that it will be released. Some hotels can send a release to your bank, though your bank still controls when the funds become available. Get a copy of your final bill.
Call your bank if the hold lingers
If the hold has not dropped off after several business days, call your bank. Explain that the hotel has already charged your final bill and ask if they can release the remaining hold. Some banks can remove holds manually with confirmation from the merchant.
Prepay when possible
If you prepay your room when booking, the hotel may only need to hold the incidental deposit at check-in, which reduces the amount tied up. Prepaid rates sometimes come with stricter cancellation policies, so weigh that tradeoff.
The same thing happens with rental cars and gas stations
Hotels are not the only places that use holds. Rental car companies typically place holds for the estimated rental cost plus a deposit, and debit card users may face larger holds, extra requirements, or credit checks. Gas stations often place a temporary hold when you pay at the pump. Cruise lines may place holds for onboard expenses.
If you travel with a debit card, assume any business that does not know your final bill in advance may place a hold.
When debit makes sense
Using a debit card for travel is not always a bad idea. Some travelers avoid credit cards to keep their spending in check, or because they do not qualify for one. Debit works fine if you know the hold amounts, keep enough money in your account, and plan for a delay in getting the funds back.
Some travelers use a separate checking account just for travel. That way, holds do not affect money set aside for bills and everyday spending.
A quick checklist before your trip
- Find out the hotel’s incidental deposit and whether it accepts debit.
- Make sure your account can cover the room, deposit, and other expenses.
- Plan for the hold to last up to a week after checkout.
- Use a credit card if possible for hotels and rental cars.
- Keep an eye on your account during the trip.
- Call your bank if a hold does not drop off in a reasonable time.
Questions travelers often ask
Is the hold the same as being charged? No. A hold is a temporary block on funds. The actual charge happens when the hotel finalizes your bill. But with debit, the practical effect can feel the same because the money is unavailable.
Can the hotel keep the deposit? Only if you incur charges, such as room service, damage, or smoking fees, depending on the hotel’s policy. Otherwise, the deposit portion should be released.
Why did I see two charges? Sometimes the original hold and the final charge appear at the same time for a short period. The hold should drop off once the final charge settles. If it does not, contact your bank.
Holds at check-in when you prepaid online
Even if you paid for your room in full through a booking site, the hotel will usually still ask for a card at check-in for incidentals. That is because the booking site collected your payment, not the hotel, and the hotel needs a way to cover any charges during your stay. Expect the incidental deposit hold even on prepaid reservations, and plan your checking balance around it if you use debit.
The bottom line
A hotel debit card hold is a temporary block on your money for the room and an incidental deposit. With a debit card, that block comes out of your available checking balance immediately and can stay in place for several days after checkout. Ask about the deposit before you go, keep a buffer, and use a credit card when you can, and the hold becomes a minor detail instead of a trip-ruining surprise.